Insider’s Guide to Financial Aid
It’s no secret, but financial aid is not my strength. Essays and admissions strategy — that's my world. The FAFSA and the fine print of paying for college? I'd rather connect you with someone brilliant at it.
And my go-to guy gentleman? Carl Buck.
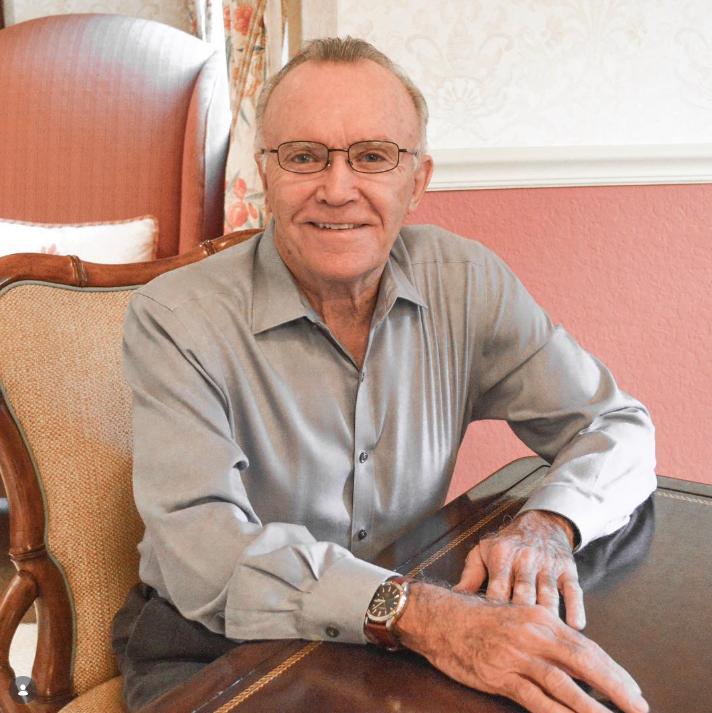
Carl spent his career on the other side of the financial aid desk — as the aid director at Rice, at Rutgers, and more. I've sent him dozens of families over the years, and they come back saying the same thing: nobody knows the inside of that office like Carl. He's also one of the most generous, articulate people I know on any of this.
And the timing is why this couldn't wait. The 2027–28 FAFSA is already open in a beta version, and opens for everyone on October 1. So if you've got a senior, this is your two-week head start.
Here's the best of what Carl shared.
1. Start early — practice the FAFSA junior year
Let me start with what bad timing cost my own family.
During COVID, my middle daughter finished her junior and senior years in one. By the time we realized she'd graduate a year early, it was almost Christmas — too late for the early application round. So we applied regular. The next fall, she met classmates with lower GPAs and test scores who got merit aid she didn't get. The only difference between them? When they applied. She ended up taking a loan she might not have needed.
Me: So how early is early enough?
Carl: Sooner than most think. Most families wait until senior year to even learn the process. I tell them: do a practice run during junior year — fill out a FAFSA for real, before it counts.
Me: But how would I even know if I was getting something wrong?
Carl: That's exactly why you practice. Three things catch people:
over-reporting assets you never had to list
missing a form or deadline
and getting blindsided by the number the formula gives you — your Student Aid Index, which is what a school expects your family to pay.
Run it once as a junior, so it’s not a shock senior year, when it's too late to fix or do anything about it.
2. FAFSA assets: what to report, what to skip
Most of the FAFSA is what you'd expect. The part that trips families up is the asset question. How? They usually report too much.
Me: So what actually counts?
Carl: Report the money you can put your hands on — cash, checking and savings, a brokerage account, crypto, a 529 for your student. Leave off the big ones: your home, your retirement accounts, a small business, life insurance, and any 529 set aside for a sibling. Those don't count — so don't hand them over.
Me: Does it matter whose name the money is in?
Carl: More than most people realize. A dollar in your student's name counts against them at 20%. That same dollar in your name counts at under 6%. So the savings account you opened in their name, with the best intentions, can cost you more than the same money sitting in yours.
And even with all the changes going on in the law, there's one piece of genuinely good news, especially if grandparents are pitching in: since 2024, money from a grandparent's 529 no longer counts against your student on the FAFSA at all. It used to cut aid by up to half the gift. Now that penalty is gone.
3. How to appeal (Hint: the aid office is on your side)
The most valuable thing I learned from Carl nearly 15 years ago was this: the person across that financial aid desk is not your adversary. They're your advocate.
Two of his stories stuck with me. A dad once sat in Carl's office at Rutgers, quietly asked his son to step outside, and admitted he was about to file for bankruptcy — he just didn't want his teen to somehow carry that. Carl did everything he could for that family. Another was a bright 17-year-old student living out of his car, estranged from his parents; Carl called the aid director at the student's dream school, told the story, and the school reclassified the teen as independent, which gave him a far bigger aid package. That young man wrote Carl a thank-you letter years later.
Me: So the story really can change the number?
Carl: It can — but you need truth and proof. A job loss, a death, an income drop, with documentation. And that proof doesn't have to be an official form. A letter from your doctor, your minister, your therapist, an employer — someone who can speak to what your family is going through. Appeals often go before a weekly committee, so the relationship a student or family builds matters. If your counselor knows your story, they can fight for you in the meetings when decisions get made.
Me: Anything families miss here?
Carl: Two things. First, the sibling discount is gone. There used to be a break for having more than one child in college at once. That's been eliminated, so a family with two in school can see their expected contribution double. If that's you, ask the aid office directly whether they have institutional funds to help.
Second, the school builds a total price for you — tuition plus a set budget for housing and food. Your aid gets calculated against that total. But the FAFSA no longer asks where your student will live, so if the office assumes they're commuting from home, they use a smaller housing budget — and your aid is figured against a smaller number. If your student is moving into a dorm, say so. Room and board is real money, often more than $10K a year, and it should be in the math.
4. College money when you “make too much” for aid
This one's for you if you've been told (or believe) your family earns too much for need-based aid.
Carl: I had a student at Rice — bright kid, family made too much to qualify. He got a merit scholarship, but no need money. So I told him: before you leave campus today, walk over to the College of Engineering, introduce yourself, and get on their list. If the scholarship money's already spoken for this year, you're first in line when a student they admitted goes to MIT instead.
Me: And who does that — the parent or the student?
Carl: The student. They're the one enrolling. They must be assertive, not aggressive — proactive. (And, yes, this is a place where they might need coaching first.)
Me: Why the department, and not the main aid office?
Carl: Because the admissions office recruits; they don't retain. The money to build out a freshman class is front-loaded. But departments run their own fundraising (with alumni, for example), and some are far wealthier than others — engineering versus history, say. Those scholarships come up every year, and a professor who thinks highly of your teen can walk into that committee and make their case.
One more thing: on the federal form, there's nowhere to ask for work-study. It's need-based, it lowers your borrowing, and you have to request it. (Get a library job, for example, and your teen gets paid to mostly do their homework.)
Quick hits: the CSS Profile, hidden costs & more
Carl and I talked for about 45 minutes. You can go deeper and hear the whole conversation right here. For now, the quick version of a few more highlights:
Do families need to complete the CSS Profile? Only if their teen applies to one of the ~300 schools that use it — mostly selective privates like Vanderbilt, Rice, or Boston University (where families under roughly $150–200K can go tuition-free — and Duke, for NC and SC families), the extra form is worth it. Applying only to state schools? You can skip this one. More on those free-tuition schools →
Is the offer final? Not always. With a better offer in hand, you can ask if the college can increase the aid for your family.
Does the sticker price mean anything? Almost no one pays it. Every college is required to post a net price calculator on its website — run it, and you'll see your family's real estimate, not the scary number on the brochure. Why the sticker price is fiction →
What do families forget to budget for?
Greek life can add around $10K a year.
A "four-year" degree often runs five (or more) — so ask for the real four-year rate.
Any easy ways to spend less?
A relative's spare room that first year can save you a full housing bill.
Tuition reciprocity: some states let you pay near in-state rates at out-of-state schools, so crossing a state line doesn't always mean the full non-resident price.
Your financial-aid to-do list
If you do only a few things, do these:
Start the FAFSA. It's open in beta now. File it even if you're sure you won't qualify — many schools won't give you their own aid, sometimes not even merit scholarships, without one on file, and federal loans need it too.
Skip the assets that don't count. Your home and your retirement stay off the form.
Book time with the aid office early — don't wait for the offer letter. Bring your story, start building a relationship.
If you "make too much": have your teen introduce themselves to their department and ask about
Ask for work-study. It's need-based, so it’s not for every family — but if your teen might qualify, ask, because it has to be requested.
Carl's last word is where we’ll wrap up: you are the advocate. You can hand the paperwork to AI if you like, but what moves a decision in your favor is a real person who knows your family — and that means making the connection yourself, face to face, by phone, or over Zoom. Often, getting money comes down to relationships.
If your family wants real, one-on-one help with the financial side, Carl is who I trust — Carl Buck, College Funding Solutions buckcollegefunding.com. In our longer interview, he also walked me through a new diagnostic tool on his site, rprx.life — and I think that one could be genuinely useful for a lot of families trying to get a clear read on where they stand. Worth a look, and worth hearing him explain it himself. Tell him I sent you.

With love, a two-week head start on the FAFSA, and a reminder that the money part of college can be far more workable than it sometimes feels,
Christy Sharafinski
Your go-to college essay + admissions mentor